
People ask one question: how many dollars of dwelling coverage must I carry? The honest answer is that the number comes from a test, not a table. Your lender checks your policy four ways. The lender may be the investor that will buy your loan. The four checks are how a loss is paid, how large the deductible can be, who is named on the policy, and whether the home sits in a mapped flood zone. This post walks through each test at the source rule. It shows the math on one worked house. It ends with the Massachusetts law that caps what a lender may demand. Other basics are on the home insurance cost guide, so we do not repeat them here. Those are what a hazard policy is, why escrow exists and how force-placed insurance works.
The short version: four tests, no universal dollar figure
| Test | The rule as published | Source and date |
|---|---|---|
| How losses are paid | Replacement-cost basis, with the exception of roofs. A policy that provides these terms is deemed to provide sufficient coverage. | Fannie Mae Selling Guide B7-3-02, effective 08/05/2026 |
| Deductible ceiling | No more than 5% of the property insurance coverage amount, for every required peril, including separate windstorm or wildfire deductibles. | Fannie Mae Selling Guide B7-3-02, effective 08/05/2026 |
| Who is named | A standard or union mortgagee clause without contribution; loss-payable clauses are not acceptable. All titleholders are named insureds. | Fannie Mae Selling Guide B7-3-08, dated 12/14/2022 |
| Flood | Required when the home is in a Special Flood Hazard Area, or in a Coastal Barrier Resources System or Otherwise Protected Area regardless of flood zone. Amount is the least of three numbers (below). | 42 U.S.C. 4012a; Fannie Mae B7-3-06, updated 02/07/2024 |
All four rows were read at the primary source on 2026-10-06. Freddie Mac publishes its own parallel requirements in Chapter 4703 of its Seller/Servicer Guide; this post quotes Fannie Mae because that was the version available to read in full on the day of writing. Your lender may add overlays, so its written requirement controls.
Notice what is missing. No row says 80% of the home's value, 100% of the loan balance, or any fixed multiple. The current Fannie Mae text for one- to four-unit homes tests how the policy pays a loss instead. The rest of this post shows why that means "insure the rebuild." It also shows where a lender's own extra rules, called overlays, can push the number higher.
Test one: replacement cost, not market value, not the loan balance
Fannie Mae's rule for one- to four-unit properties says the policy must pay on a replacement-cost basis, except for roofs. Replacement cost means the cost to rebuild with new materials. Fannie Mae says policies with those terms are deemed to provide sufficient coverage. It also asks for a Special coverage form or the equivalent. At a minimum, that form must cover fire or lightning, explosion, windstorm (including named storms), hail, smoke, aircraft, vehicles, and riot or civil commotion. A second rule is in the general requirements section. It requires the insurer to hold at least one of these ratings: A.M. Best B, Demotech A, Kroll Bond Rating Agency BBB, or S&P Global BBB. A cheap policy from an unrated company can fail the lender's check even if the dollar limit is right.
The roof exception matters. A policy can pay for the roof at actual cash value and still pass. Actual cash value is the price after subtracting wear and age. That is the lender's floor, not a good plan. A roof paid at a worn-down value can leave a large gap after a storm. So read the roof endorsement on your own policy.
Three numbers that get confused
The NAIC consumer guide (2022 edition) makes the point plainly. Your dwelling coverage should equal the full replacement cost of your home. Replacement cost and market value are not the same. Market value includes the land and moves with the housing market. Replacement cost is the cost to rebuild with materials of similar kind and quality. The loan balance is a third number that has nothing to do with the building. The table uses one example house to show how far apart the three can sit.
| Figure | Amount | What it measures |
|---|---|---|
| Purchase price | $600,000 | Land plus structure plus location premium |
| Loan balance after 20% down | $480,000 | What the lender is owed |
| Estimated cost to rebuild the structure | $410,000 | Labor and materials to replace the dwelling, excluding land |
Illustrative figures chosen to show the gap; they are not market data. Your own rebuild estimate comes from your insurer or an appraiser's cost approach, not from this table.
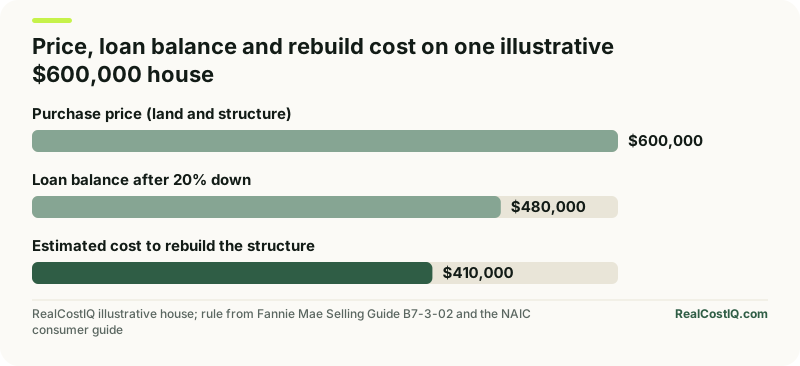
On this house, a Coverage A limit of $410,000 on a replacement-cost policy meets the Fannie Mae test. Coverage A is the part of the policy that covers the dwelling. A limit of $480,000 (the loan balance) would also pass, because the test is how the policy pays. But it would buy $70,000 of coverage that can never be paid. A replacement-cost policy pays to rebuild, not to pay off the loan. Some lenders tie the requirement to the loan balance on a home that costs less to rebuild. The Massachusetts law below deals with that case.
Test two: the maximum deductible
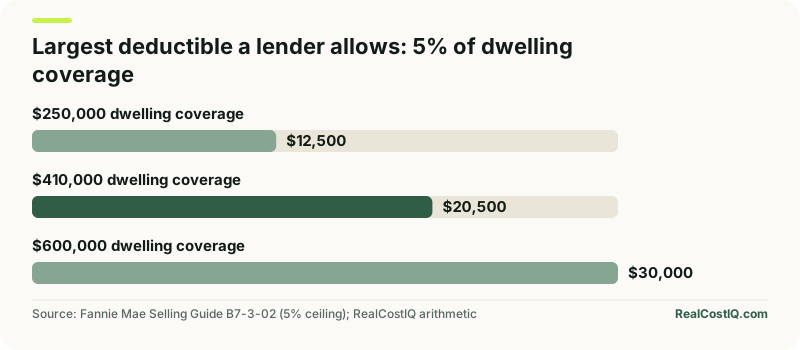
The deductible is the part of a loss you pay before the insurer pays. This is the one place the rule is a clean percentage. Fannie Mae allows a maximum deductible of 5% of the property insurance coverage amount for all required perils. A peril is a cause of loss, such as fire or wind. Some policies carry separate deductibles for perils like wind or wildfire. Each one must stay under the 5% line. The percentage applies to your Coverage A limit, not to the home's price.
| Dwelling coverage (Coverage A) | 5% ceiling | Typical flat deductible for comparison |
|---|---|---|
| $250,000 | $12,500 | $1,000 to $2,500 flat |
| $410,000 (the illustrative house) | $20,500 | $1,000 to $2,500 flat |
| $600,000 | $30,000 | $1,000 to $2,500 flat |
The ceiling column is arithmetic (coverage x 0.05). The flat-deductible column is a plain-language range for context, not a sourced market average; request an actual quote to see what your insurer offers.
The ceiling rarely matters for a flat dollar deductible. It matters a lot for percentage deductibles. In some coastal and storm-prone areas, wind and hail deductibles are a percentage of the dwelling limit. A 5% wind deductible sits exactly at the line and passes. A 10% one fails the test. If a quote shows a percentage wind deductible, do the math before you sign. A policy that fails is sent back at underwriting, usually days before closing.
Test three: the mortgagee clause and the named insured
This test costs nothing to pass if you check it early. A mortgagee clause is the part of your policy that names the lender. For one- to four-unit homes, Fannie Mae requires a standard or union mortgagee clause without contribution, customary to the property's location. It says that loss-payable clauses are not acceptable. In plain terms, the clause protects the lender's right to be paid even if you do something that voids the policy as to you. A loss-payable clause is weaker. It does not give the lender that separate protection.
- Spelling matters. The lender's name must appear as the mortgagee, followed by "its successors and/or assigns," and its mailing address. If the lender is not the servicer, add the servicer's name and address too. A typo in the clause is a common reason a binder is rejected. A binder is the short proof of coverage you give the lender.
- MERS cannot be the mortgagee. MERS is a loan-tracking registry. If your loan is registered with MERS, the guide says MERS must not be named as mortgagee or loss payee. The servicer's name goes there instead.
- Every titleholder is a named insured. The policy must name everyone who holds title. A spouse on the deed but not on the policy can fail the test.
- The policy must give written notice of cancellation to the named insured and the mortgagee(s) before the insurer can cancel. Ask your agent to confirm that it does.
Test four: flood, the only federal mandate
Flood is the one test written into federal law. Under 42 U.S.C. 4012a, a regulated lender may not make or renew a loan on a built-up property in a special flood hazard area unless it has flood insurance. Fannie Mae's flood section sets the amount at the least of three figures: full replacement cost, the unpaid balance, and the NFIP maximum. FloodSmart lists the NFIP building limit as $250,000, so that cap usually decides it. The gap above it is your choice. For the full rule, the worked example and the gap, read how much flood insurance you need. To price a policy for your address, use the flood insurance cost calculator.
Getting the replacement-cost number right
The lender's test is about replacement cost, so the number that matters is your rebuild estimate. There are only a few good ways to get one.
- Your insurer's estimator. Most carriers run a cost tool that uses square footage, construction type, roof, finishes and ZIP code. It is free, and the policy is written against its number. But it is only as good as the inputs. The usual error is the wrong finish level, such as builder-grade versus custom.
- The appraisal's cost approach. A lender's appraisal often has a cost-approach section. That gives you a second opinion you already paid for, so ask for it. It is not an insurance quote. But it will show you if the carrier's estimate is far off.
- A contractor or estimator you hire. For an older or unusual home, an independent rebuild estimate can prevent a large shortfall.
- An endorsement that moves the risk. An endorsement is an add-on to your policy. Guaranteed replacement cost pays to fully rebuild the home. An inflation guard endorsement raises the dwelling limit each year to keep up with inflation. The NAIC guide lists both as ways to raise coverage. It adds an ordinance or law endorsement. That one pays the extra cost of rebuilding to codes that did not exist when the home was built. A lender does not require these. But they decide whether a total loss is truly covered.
The NAIC guide also warns that the insurer may pay less on a claim if your dwelling coverage drops below 80% of the full replacement cost. So the 80% figure exists. But it is an insurer's coinsurance-style penalty, not the lender's rule. After a few years of rising building costs, a limit set at closing can slide under that line. That is another reason to get a new quote for the dwelling limit at every renewal.
Massachusetts: the statute that caps what a lender may require
Massachusetts is the clearest case of the law pushing the other way. General Laws chapter 183, section 66 says that a bank, lending institution, mortgage company or any mortgagee doing business in the commonwealth shall not set a certain condition. When making a mortgage loan, it may not require the borrower to buy casualty insurance above the replacement cost of the buildings or appurtenances. The statute adds that "replacement cost," "buildings" and "appurtenances" are read in line with the policy forms approved by the commissioner of insurance.
Two features of that text matter for a Massachusetts buyer. First, it is a ceiling, not a floor. A lender cannot demand more than replacement cost, and the law says nothing about the minimum. Second, it speaks of the buildings and appurtenances, so land value cannot count toward the requirement. Together, these rule out the "insure to the loan balance" shortcut whenever the loan balance is higher than the cost to rebuild. On a Boston-area condo or a lot with high land value, that is routine.
| Item | Amount |
|---|---|
| Purchase price | $600,000 |
| Loan balance | $480,000 |
| Insurer's replacement-cost estimate for the structure | $410,000 |
| Most a covered lender may require under G.L. c.183 s.66 | $410,000 |
| Amount that would exceed the statute | Any requirement above $410,000, such as the $480,000 loan balance |
Illustrative arithmetic only. It shows how the cap would work if it applies to your lender; it is not legal advice.
The federal preemption wrinkle
The statute does not apply to every lender with equal force. In September 2012, a federal court in Massachusetts ruled in Silverstein v. ING Bank, fsb. It held that the federal Home Owners' Loan Act overrode this very limit for a federal savings bank. The limit falls on the list of state laws that the HOLA rules say are overridden. The case is summarized in an Orrick client alert. The borrower had said the bank required coverage equal to the outstanding principal balance, which was above replacement cost.
In practice, the cap is real law. But whether a given lender can be held to it can depend on what kind of institution it is. The 2012 ruling also came before a change in federal law. 12 U.S.C. 1465 was added by the Dodd-Frank Act. It says preemption for federal savings associations is decided under the standards for national banks. It also says the chapter does not take over any area of State law. So Silverstein's reasoning may not reach newer loans. Treat the statute as strong leverage, not a guarantee, and see the statute text. The practical move is to send the lender your insurer's replacement-cost estimate in writing. Then ask what figure it requires and under what authority. A lender selling the loan to Fannie Mae already has the Fannie Mae test in front of it. That test is based on replacement cost.
VA loans: a general standard, not a formula
VA-guaranteed loans require that the home be insured enough against hazards. The VA rule is general, not a formula. 38 CFR 36.4329 calls for policies bought and kept in an amount enough to protect the security against the risks or hazards it may face, to the extent customary in the locality. It adds a separate flood rule in special flood hazard areas. It sets no dollar percentage like the Fannie Mae and FHA text above. The advice is the same as elsewhere. Ask your VA lender for its written insurance requirement before you buy a policy, and give it the replacement-cost estimate. Say the lender asks for coverage at the loan balance on a home that would cost less to rebuild. Then you are in the same spot as the Massachusetts example.
What happens if your policy falls short
Your policy may lapse or fail the tests after closing. Then the servicer can buy force-placed coverage and bill you. The rules on notice and charges are on the home insurance guide. The short version is that it costs more and protects less than a policy you buy yourself. For flood, the law is blunter. If you do not buy the required amount within 45 days of the lender's notice, the lender must buy it. It may charge you for the premiums and fees.
A pre-closing checklist
- Ask the lender for its written insurance requirement, including any overlay above the investor minimum.
- Get a replacement-cost estimate from the insurer and keep a copy.
- Confirm the policy is written on a replacement-cost basis (roof excepted) on a Special form.
- Multiply Coverage A by 5% and compare every deductible, including percentage wind and hail deductibles, against that figure.
- Check the mortgagee clause wording, the servicer's name and address, and that every titleholder is a named insured.
- Look up the flood zone. If it begins with A or V, price NFIP coverage and decide whether to add excess flood above $250,000.
- Send the binder and the declarations page to the lender, and confirm receipt before closing day.